- A consolidation loan moves your debt — it doesn’t erase it. The new loan’s total cost must be clearly lower.
- It works when your new APR is meaningfully lower and you stop adding new debt on the freed-up cards.
- Compare APR, origination fees and term — never judge by the monthly payment alone.
- Example: $12,000 at 26% APR consolidated at 14% saves roughly $2,900 in interest.
- What Is Debt Consolidation?
- How Debt Consolidation Works — Step by Step
- When Consolidation Actually Saves You Money
- When Consolidation Is a Bad Idea
- What to Compare When Shopping for a Consolidation Loan
- Alternatives Worth Considering
- How to Apply Without Hurting Your Chances
- Should You Consolidate? A 10-Minute Worksheet
- 7 Mistakes That Turn Consolidation Into a Debt Trap
- Frequently Asked Questions
Juggling five payments a month — three credit cards, a store card, a small personal loan — is exhausting. Miss one date and late fees pile on; pay only minimums and balances barely move. Debt consolidation targets exactly this: one loan, one payment, one interest rate, ideally lower than the average rate you pay now.
But consolidation is a tool, not a rescue. Done right, it can save thousands in interest and get you debt-free years earlier. Done wrong, it stretches expensive debt over more years and costs you more. This guide covers the full picture — real math, honest warnings, alternatives, and a clear action plan — so you can decide with confidence.
What Is Debt Consolidation?
Debt consolidation means taking out one new loan and using it to pay off multiple existing debts in full. After that: one lender, one monthly payment, one interest rate.
Most commonly, people use an unsecured personal loan: the lender deposits a lump sum (or pays your creditors directly), and you repay it in fixed monthly installments over 2–7 years.
Other methods exist — balance-transfer cards, home equity loans, debt management plans — but this guide focuses on the personal loan route, the most widely available and easiest to compare.
How Debt Consolidation Works — Step by Step
- List every debt — balance, APR, minimum payment, remaining term. You can’t compare offers without this.
- Check your credit. Your score largely decides your APR — check it before applying.
- Shop 3+ lenders on APR, origination fees, term and prepayment penalties — not just the monthly payment.
- Do the total-cost math: new loan total (payments + fees) vs. total remaining on current debts. The new total must be clearly lower.
- Pay off old debts immediately once funded — don’t let the money sit in your account.
- Freeze the old credit lines. The most-skipped step, and the top reason consolidation fails.
When Consolidation Actually Saves You Money
Consolidation helps when all three hold true:
- Your new APR is meaningfully lower than your current weighted average. 2026 data puts consolidation loans around 20% APR on average — useful only if your cards charge more (many charge 24–29%).
- Total cost is lower, not just the monthly payment. A longer term can shrink the payment while growing total interest.
- You stop adding new debt. Consolidation without a spending change just rearranges the problem.
A worked example
Say you owe $12,000 across three cards at an average 26% APR, paying $400/month. You would pay roughly $5,700 in interest and take about 44 months to clear it.
Now suppose you get a $12,000 consolidation loan at 14% APR over 36 months. Your payment becomes about $410/month — nearly the same — but total interest drops to roughly $2,760. You save about $2,900 and finish 8 months earlier. That is consolidation working.
Want to check your own numbers? Use our EMI Calculator — enter your current debts as one scenario and the consolidation offer as another, and compare the total interest side by side.
Myths vs facts
- Myth: Consolidation cuts what you owe. Fact: It reorganizes the same principal — only the interest and timeline change.
- Myth: It always helps your credit. Fact: Only with on-time payments and no new debt.
- Myth: One payment solves the problem. Fact: Simplicity isn’t stability — habits decide.
When Consolidation Is a Bad Idea
- The APR isn’t really lower. With fair or poor credit, your loan may carry 25–30% APR — no better than your cards, plus a fee on top.
- Fees eat the savings. A 5–8% fee on $15,000 is $750–$1,200 added on day one — subtract it from projected savings.
- The term is much longer. $10,000 at 12% over 7 years costs ~$4,700 in interest — more than the same debt at 22% cleared in 3 years (~$3,700).
- You haven’t fixed the cause. If debt came from overspending, a new loan resets the trap — fix the budget first.
- You’re pledging your home to pay unsecured debt — converting defaultable debt into debt that can take your house.
What to Compare When Shopping for a Consolidation Loan
| Factor | What to look for |
|---|---|
| APR | The most important number. Must beat your current weighted average by a clear margin. |
| Origination fee | 0–8% is typical. A “low APR” with a big fee can lose to a slightly higher APR with no fee. |
| Term length | Shorter = less total interest. Don’t pick 7 years for a smaller payment unless the total still wins. |
| Prepayment penalty | Avoid loans that punish early payoff. |
| Fixed vs variable APR | Fixed keeps payments predictable. Variable can rise — confirm which you’re signing. |
| Debt-to-income ratio (DTI) | Monthly debt payments ÷ gross monthly income. Many lenders prefer under ~40–45% — know yours first. |
| Funding timeline | Online lenders often fund in 1–7 business days; direct-to-creditor payoff is fastest. |
| Late fees & hardship options | Check the late fee and whether hardship deferment exists. |
| Direct creditor payoff | Some lenders pay creditors directly — removing the temptation to spend the lump sum. |
Alternatives Worth Considering
- Balance-transfer card (0% intro APR). With good credit and modest debt, 12–21 months at 0% can beat any loan — but watch the 3–5% fee and the revert rate if you don’t finish in time.
- Debt management plan (DMP). A nonprofit agency negotiates lower rates; you make one payment to the agency. No new loan needed; typically 3–5 years.
- Aggressive avalanche payoff. No new credit: minimums everywhere, extra cash to the highest-APR balance first. Cheapest if you can sustain it.
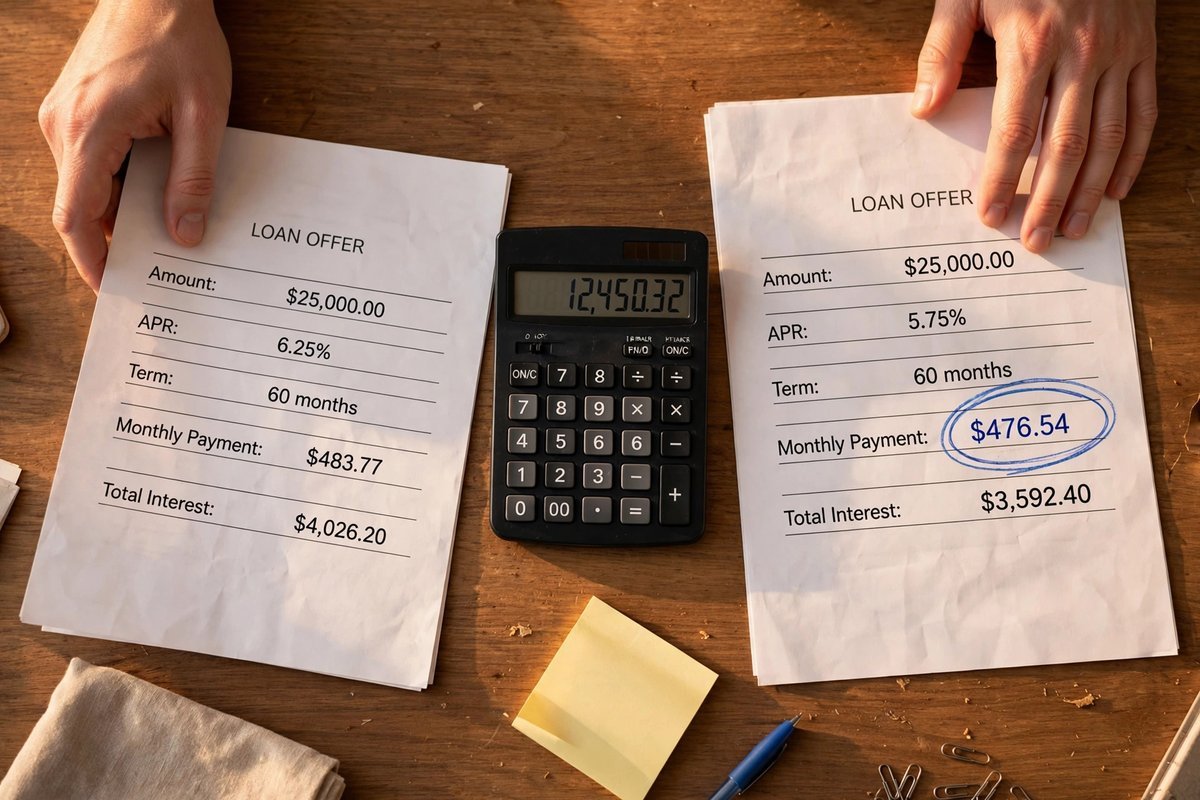
Side-by-side cost example — $15,000 in card debt at 23% APR (illustrative figures; actual rates, fees and approval vary by lender and your credit):
| Option | Monthly payment | Time to payoff | Total interest + fees |
|---|---|---|---|
| Keep the cards (23% APR) | ~$450 | ~54 months | ~$9,150 interest |
| Consolidation loan (11% APR, 36 mo, 4% fee) | ~$491 | 36 months | ~$2,678 interest + $600 fee |
| Balance transfer (0% for 18 mo, 4% fee) | ~$833 | 18 months | $600 fee, if cleared in time |
The transfer is cheapest but demands ~$833/month and a high limit; the loan costs more but holds payments near $491 with a fixed payoff date. Debt settlement (major credit damage, possible tax on forgiven debt) and bankruptcy (severe credit impact) are separate last resorts — not consolidation.
How to Apply Without Hurting Your Chances
- Pre-qualify first (soft check, no score impact) and collect 3+ real offers.
- Compare total cost, not monthly payment. Include every fee.
- Apply formally once, with the best lender — keep all applications within 14–30 days.
- Read the fine print: confirm fixed APR, note the payoff date, check prepayment penalties.
- Pay off old debts the same week funds arrive; set the new loan on autopay.
Tip: include at least one credit union or community bank — they often beat online lenders on APR for members. Terms vary by lender and state, so verify current rates on their site before applying.
Not sure what payment fits your income? Our Loan Eligibility Calculator shows what you can safely borrow after existing obligations.
Should You Consolidate? A 10-Minute Worksheet
Run your own numbers in four steps — all you need is your latest statements.
Step 1 — Inventory your debts.
| Debt | Balance | APR | Min. payment |
|---|---|---|---|
| Card A | $5,000 | 24% | $125 |
| Card B | $4,000 | 27% | $110 |
| Store card | $3,000 | 21% | $75 |
| Total | $12,000 | — | $310 |
Step 2 — Weighted average APR. ($5,000 × 24 + $4,000 × 27 + $3,000 × 21) ÷ $12,000 = 24.25%. Your offer must beat this by a clear margin — aim for 3–5 points lower after fees.
Step 3 — Price the offer. Example: $12,000 at 14% APR over 36 months with a 3% fee ($360). Payment ≈ $410/month; total ≈ $15,122. Current path — $400/month at ~26% — costs ~$19,600 over ~49 months. Savings: ~$4,480, ~13 months sooner.
Step 4 — Gut check. Say yes only if: APR gap ≥3 points, total cost clearly lower, payment fits your budget, old cards frozen the same week.
If the math wins:
- Pre-qualify with 3+ lenders (soft checks); pick the shortest affordable term.
- Zero every old balance the same week; set the new loan to autopay.
- Delete saved card numbers; build a $500–$1,000 emergency buffer; check your credit report in 60 days.
7 Mistakes That Turn Consolidation Into a Debt Trap
- Shopping by monthly payment alone. A smaller payment over 7 years can cost double the interest of a larger one over 3 — total cost is the only scoreboard.
- Ignoring the origination fee. 6% on $15,000 adds $900 on day one, and you pay interest on it.
- Consolidating only part of the debt. Leftover high-APR balances keep compounding — every balance needs a plan.
- Rate-shopping over months. Scattered applications, scattered inquiries — do them all within 14–30 days.
- Missing that the rate is variable. Confirm fixed APR before signing.
- Raiding retirement. A 401(k) loan can come due immediately if you change jobs — taxes and penalties included.
- Changing nothing about spending. Freed-up cards get refilled — the #1 reason consolidation fails.
Frequently Asked Questions
Does debt consolidation hurt my credit score?
Only slightly and temporarily — the hard inquiry and new account may dip your score a few points. On-time payments and falling credit utilization usually lift it within months. But utilization only improves if you stop adding new charges — and one 30-day-late payment hurts far more than the inquiry.
Can I consolidate with bad credit?
It’s harder and often not worthwhile — offers may carry APRs as high as your cards, plus fees. Until your score improves, a nonprofit debt management plan or the avalanche method usually serves you better. See our guide on getting a loan without a credit check.
Should I close my old credit cards after consolidating?
Don’t close your oldest cards — that shortens your credit history and can hurt your score. Remove them from your wallet, delete saved card numbers, and keep one for small bills you pay in full monthly.
Is a longer term ever the right choice?
Sometimes — if the alternative is missing payments and wrecking your credit. A longer term you can actually pay beats a shorter one you default on. Just know you’re buying that safety with extra interest, and pay extra whenever you can.
What documents will the lender ask for?
Typically: government ID, proof of income (pay stubs or tax returns), bank statements, and details of the debts to consolidate. Our full checklist is in Documents You Need to Apply for a Loan.
What credit score do I need for a debt consolidation loan?
There’s no universal cutoff — it varies by lender. Roughly 670+ unlocks the competitive APRs that make consolidation worthwhile. Below that, offered rates may match your cards, erasing the benefit. Pre-qualify with a few lenders (soft checks only) to see your real numbers.
Can I consolidate student loans, medical bills, or payday loans?
Most personal loans cover credit cards, medical bills, store cards, and other unsecured personal loans — but check with your lender, since some exclude certain debt types. The big exception is federal student loans: rolling them into a private loan permanently forfeits income-driven repayment, deferment, and potential forgiveness.
Balance-transfer card or personal loan — which is better?
Under roughly $5,000–$7,000, with good credit and a plan to clear it within the 0% window (12–21 months), a balance-transfer card usually wins — even after the 3–5% fee. For larger balances, a personal loan’s fixed rate is safer: missing the card’s deadline triggers 24–29% revert APR. Some do both. Compare in our EMI Calculator.
What happens if I miss a payment on my consolidation loan?
Expect a late fee (it’s in your loan agreement), a credit-report mark at 30+ days late, and possibly a penalty APR. One slip is recoverable — contact your lender immediately, since many offer hardship arrangements — and set up autopay. Missing the single payment you consolidated down to is the fastest route back into trouble.
I’m already behind on payments — can I still consolidate?
It’s harder: missed payments lower your score, pushing offered APRs up — sometimes past the point where consolidation helps. If you’re 30–90 days behind, talk to a nonprofit credit counseling agency first: a debt management plan can negotiate lower rates without a new loan. And paying past-due accounts current stops further damage — some newer scoring models ignore paid collections.
How do I spot a debt consolidation scam?
Real lenders never guarantee approval, charge upfront fees before funding, or promise to “make your debt disappear” — that’s debt settlement, with serious credit damage. Red flags: pressure to sign now, no physical address, being told to stop paying creditors. Verify any company via the CFPB or your state attorney general.
Can I just negotiate with my creditors instead?
Sometimes — and asking costs nothing. Some issuers will lower your APR, waive fees, or offer a short hardship program if you call and explain. Get any deal in writing — for one or two high-rate balances, it can be enough.
Educational content only — not financial advice. Loan terms, rates and approval depend on the lender and your profile. See our Financial Disclaimer.