- Borrow for urgent repairs and value-adding upgrades — with a written quote, not a guess.
- Match the product to the project: personal loan for small/fast jobs, home equity loan for big planned ones, HELOC for phased work.
- Add a 10–15% contingency and never pay a contractor 100% upfront.
- Watch for red flags: pressure tactics, ‘preferred lender’ pushes, no license, cash-only deals.
- What Is a Home Improvement Loan?
- When Borrowing for Renovation Makes Sense
- When You Should NOT Borrow for It
- Personal Loan vs HELOC vs Home Equity Loan
- How to Get the Loan — Step by Step
- Contractor Red Flags (Borrower’s Edition)
- The True Cost: A Worked $15,000 Example
- Comparing Lenders: The 8-Point Checklist
- 7 Costly Mistakes to Avoid
- Your Action Plan: What to Do Next
- Frequently Asked Questions
A leaking roof, a kitchen from 1987, a bathroom that needs more than a prayer — home repairs rarely wait for the “right time.” In 2026, home improvement is one of the top reasons people take personal loans, with average disbursements around $18,700 according to lending marketplace data. A personal loan can be a smart way to fund a renovation — but only if the project is worth more than the interest you will pay.
This guide covers when borrowing makes sense, how each option compares, and how to borrow without getting burned.
What Is a Home Improvement Loan?
It is simply a personal loan used for renovation or repair — there is no special “home improvement loan” product at most lenders. You apply like any personal loan: credit and income check, lump-sum deposit, fixed monthly installments over 2–7 years.
What makes it different is purpose: the money goes into your property, which can protect or increase its value — unlike a vacation loan.
A personal loan is unsecured: no lien, no appraisal, no equity needed — so funding is fast (typically 1–3 business days), but APRs run higher. Typical terms: $1,000–$50,000 over 24–84 months, fixed rate and payment, deposited to your account.
When Borrowing for Renovation Makes Sense
- Urgent repairs. Roof, plumbing, electrical, HVAC, structural — delaying them makes them more expensive. A $4,000 roof fix now beats $15,000 in water damage later.
- Value-adding upgrades. Kitchens, bathrooms and energy upgrades return a solid share of their cost; modest mid-range projects recoup best.
- Energy upgrades that pay you back monthly. Insulation or a heat pump cuts utility bills monthly — e.g. $5,000 at 12% APR/36 months costs ~$166/month, minus ~$45/month in energy savings = ~$121 net.
- Your insurer or mortgage requires it. Some insurers will not renew a policy on a home with an aging roof or faulty wiring.
- You have stable income and a clear budget. Written quote, 10–15% contingency, and a comfortable payment — check our Loan Eligibility Calculator.
- The math beats waiting. If saving takes 3 years but the repair is urgent now, paying some interest can be rational.
When You Should NOT Borrow for It
- The “improvement” is purely cosmetic and you are stretching. A $25,000 luxury kitchen on a tight budget at 18% APR leaves you house-rich and cash-desperate.
- You are borrowing against a guess. No written quote or fixed scope — just “around $20k.” This is where budgets explode.
- The monthly payment strains you. If one missed paycheck would mean missing the loan payment, the renovation can wait or shrink.
- You would drain your emergency fund — and the payment leaves no margin. If the payment only fits because you skipped your safety net, shrink the project.
- You plan to sell within months and the upgrade will not move the price. If a $15,000 bathroom adds ~$5,000 to the sale price, stick to cosmetic fixes.
- You are already carrying heavy debt. Adding a renovation loan on top of maxed-out cards is a red flag — consider our debt consolidation guide first.
Personal Loan vs HELOC vs Home Equity Loan
Key split: secured options (home equity loan, HELOC, cash-out refinance, FHA 203(k)) use your home as collateral — lower rates, house at risk. Unsecured options (personal loan, credit card) do not — faster, costlier:
| Option | Best for | Typical APR* | Funding | Watch out for |
|---|---|---|---|---|
| Personal loan | $5k–$40k, fast, renters too | 10–25% | 1–3 days | Higher APR; no tax benefit |
| HELOC | Phased projects; draw as needed | 8–13%, variable | 2–6 weeks | Variable rate; home is collateral |
| Home equity loan | One big project; fixed rate | 7–12%, fixed | 2–6 weeks | Closing costs; home at risk |
| Cash-out refinance | Very large projects; replaces mortgage | Near mortgage rates | 3–6 weeks | Resets mortgage; closing costs |
| FHA 203(k) | Fixer-upper purchase + renovation in one | Near mortgage rates | Several weeks | FHA paperwork; mortgage insurance |
| Credit card | Tiny projects; 0% intro offers | 20%+ after intro | Immediate | Highest APRs |
| Savings | Non-urgent upgrades | 0% | Immediate | Zero interest, zero risk |
*Illustrative ranges — verify current rates on the lender’s site. Terms vary by lender, credit profile and state/province.
Match the loan to the project size. Under $15,000 → personal loan. $25,000–$60,000 → home equity products if you have equity and can wait. $75,000+ → cash-out refinance or FHA 203(k). Costs vary by region — get real quotes.
Worked comparison — why the product matters at larger amounts. On $40,000 over 5 years: a personal loan at 15% APR costs ~$951/month with ~$17,100 total interest; a HELOC at 9% costs ~$830/month with ~$9,800 — a gap over $7,000. (Illustrative; HELOC rates are variable.)
The 4-question test: borrow only if “yes” to all four: urgent or value-adding? written quote signed? payment fits with margin? total cost below the benefit?
How to Get the Loan — Step by Step
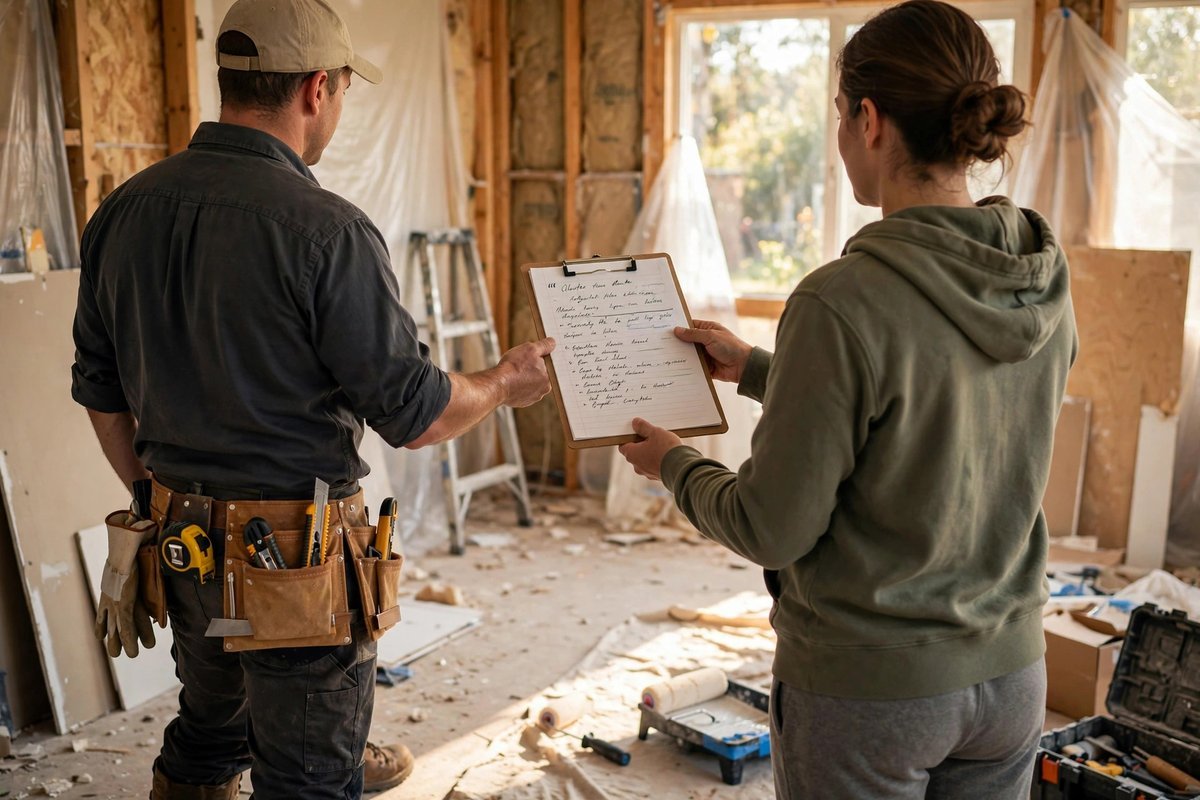
- Define the project in writing. Scope, materials, timeline. Get two itemized written quotes from licensed contractors, valid ≥ 30 days.
- Add 10–15% contingency. Borrow quote + buffer: signed quote × 1.15, rounded up. $12,000 → $13,800 → borrow $14,000.
- Check your credit and compare lenders. Pre-qualify with 3+ lenders (soft check). Compare APR, fees and term — not just the monthly payment.
- Run the total-cost math. Use our EMI Calculator to see the total interest. Is the project worth that total?
- Never pay the full amount upfront. Standard: 10–30% deposit, progress payments, balance on completion. Example for $20,000:
| Milestone | When you pay | Amount |
|---|---|---|
| Deposit | At contract signing | $4,000 (20%) |
| Demolition & framing complete | After inspection | $6,000 (30%) |
| Rough-in & drywall complete | After inspection | $6,000 (30%) |
| Final payment | After final walkthrough | $4,000 (20%) |
- Pull permits and notify your insurer. Major electrical, plumbing and structural work needs a permit — unpermitted work can void insurance claims.
- Keep receipts and a paper trail. Document every payment and change order in writing, and photograph each milestone.
Contractor Red Flags (Borrower’s Edition)
- 🚩 “Sign today, price goes up tomorrow.” Legitimate contractors give written quotes valid for 30 days.
- 🚩 Wants you to use “their” lender. Kickback arrangements exist — compare independently.
- 🚩 No license or insurance proof. Verify with your state/local licensing board — it takes five minutes.
- 🚩 Pushes you to borrow more than the project costs (“while you’re at it, take extra”).
- 🚩 Cash-only, no contract. Walk away, no matter how good the price sounds.
- 🚩 No address, no references, no online footprint. Ask for three references — and call them.
- 🚩 Asks you to sign a completion certificate before work is done. Never sign off until you have verified the work yourself.
- 🚩 Shows up uninvited after a storm. Door-to-door storm pitches are a classic setup for inflated jobs — get your own inspection first.
The True Cost: A Worked $15,000 Example
The total interest depends on APR and term. The real math on $15,000:
| Scenario | Monthly | Total repaid | Total interest |
|---|---|---|---|
| 12% APR, 3 years | $498 | $17,936 | $2,936 |
| 12% APR, 5 years | $334 | $20,020 | $5,020 |
| 18% APR, 3 years | $542 | $19,522 | $4,522 |
| 18% APR, 5 years | $381 | $22,854 | $7,854 |
Standard amortization estimates; verify current rates on the lender’s site.
Two lessons: longer terms cost more — 3→5 years at 12% saves $164/month but adds $2,084 interest. And credit quality matters — $2,936 vs $4,522 at 12% vs 18%.
Do not forget the origination fee (1–8%): 3% on $15,000 is $450, sometimes deducted from disbursement. Always add fees to the interest when comparing.
Comparing Lenders: The 8-Point Checklist
Run every offer through this checklist:
- APR, not just “rate.” APR bundles rate + most fees — 11.9% with a 4% fee can cost more than 12.5% with a 2% fee.
- Origination fee. Typically 1–8%; check if it is deducted from your disbursement.
- Prepayment penalty. Most personal loans have none — verify in writing.
- Term options. Pick the shortest term you can afford (see Section 7).
- Payment fit. Must fit with margin — test with our Loan Eligibility Calculator.
- Funding speed. “Approved” and “funded” are different events — confirm the timeline.
- Late fees & hardship options. Check the late fee, grace period, and payment-date flexibility.
- Legitimacy. Licensed in your state, verifiable reviews, no upfront fees. “Guaranteed approval” is a walk-away signal.
Why the lowest APR is not always the cheapest loan — three illustrative offers on $15,000 / 36 months:
| Offer | APR | Fee | Interest | Total cost |
|---|---|---|---|---|
| Lender A | 12.5% | 2% ($300) | ~$3,071 | ~$3,371 ✓ |
| Lender B | 14.0% | $0 | ~$3,457 | ~$3,457 |
| Lender C | 11.9% | 4% ($600) | ~$2,915 | ~$3,515 |
Lender C’s lowest APR costs the most after its $600 fee. Compare total cost (interest + fees), never the rate alone.
7 Costly Mistakes to Avoid
- Borrowing the maximum instead of the quote. At 15% APR/5 years, an extra $5,000 costs ~$2,100 in interest. Borrow quote + contingency, nothing more.
- Starting work before the loan funds. “Approved” is not “funded” — sign the start date only after the money is in your account.
- A vague contract. “Renovate bathroom — $18,000” invites disputes. Insist on line items: materials, labor, permits, timeline, milestones, change-order process.
- Paying 100% upfront. Milestone payments (Section 5) keep your leverage to the final walkthrough.
- Skipping permits. Unpermitted work can void insurance claims and force costly corrections at resale — confirm the contractor pulls permits.
- Comparing monthly payments instead of total cost. $290/month over 7 years can cost double the interest of $420/month over 4 years — compare total repaid (Section 7).
- Putting overruns on a credit card “temporarily.” At ~24% APR, a $6,000 overrun costs far more than a proper contingency. The card is never your backup plan.
Your Action Plan: What to Do Next
This week — before borrowing:
- ☐ Get 2–3 itemized written quotes (valid ≥ 30 days).
- ☐ Check your credit report; pre-qualify with 3+ lenders (soft check).
- ☐ Set your borrow number: signed quote × 1.15, rounded up.
- ☐ Run costs on our EMI Calculator and Loan Eligibility Calculator.
- ☐ Gather ID, income proof, bank statements, contractor quote — full list: Documents You Need to Apply for a Loan.
Before signing:
- ☐ Confirm permits and insurer notification.
- ☐ Payment schedule in contract: deposit ≤ 30%, balance after final walkthrough.
- ☐ Compare total cost (interest + fees) across offers — not the monthly payment.
After funding:
- ☐ Pay by milestone; photograph stages; keep every receipt in writing.
- ☐ Set up autopay immediately.
- ☐ Keep your emergency fund untouched.
Frequently Asked Questions
How much can I borrow for home improvement?
Personal loans typically go up to $40,000–$50,000 depending on the lender and your profile; home equity products go higher but use your house as collateral. Borrow for the written quote + contingency — not the maximum.
Is the interest tax-deductible?
Interest on a personal loan is never tax-deductible. Home equity loan/HELOC interest may be deductible if used to buy, build, or substantially improve the securing home — only if you itemize, subject to a $750,000 mortgage-debt cap. Confirm with a tax professional.
Personal loan or HELOC for a $20,000 kitchen remodel?
Need money within days for a single-phase project? A personal loan is simpler and faster. Stretching over months with phased payments? A HELOC lets you draw — and pay interest on — only what you need, when you need it.
Will a renovation increase my home’s value enough to cover the loan?
Sometimes partially, rarely fully. Kitchens, bathrooms and energy upgrades recoup a decent share; luxury finishes recoup less. Renovate for your needs first — treat value gain as a bonus, not the justification.
What documents will I need?
ID, income proof, bank statements. Some lenders ask for the contractor quote or project description. Full checklist: Documents You Need to Apply for a Loan.
How fast can I get the money after approval?
Personal loans commonly fund in 1–3 business days; home equity products often take 2–6 weeks. Verify timelines on the lender’s site — and do not sign a contractor start date until the money is in your account.
What credit score do I need?
No single cutoff — it varies by lender. Roughly: 670+ gets reasonable rates, 740+ the best offers, below ~640 options shrink. Pre-qualification is a soft check (no score impact).
Should I borrow the maximum the lender offers?
No — borrow the signed quote plus 10–15% contingency, rounded up. At 15% APR over 5 years, an extra $5,000 you did not need costs roughly $2,100 in interest.
Can I use a personal loan for a rental property — or a home I don’t own yet?
Yes — a personal loan is not tied to any property. Caution: borrowing right before a mortgage closes can affect approval — check with your mortgage lender first. Renters: confirm with your landlord in writing.
What if the project runs over budget halfway through?
Spend your contingency first. Get every change order in writing with a price — verbal “while we’re at it” additions are the classic budget killer. If the overrun exceeds your buffer, pause and re-scope.
Can I pay off the loan early if I sell the house?
Usually yes — it is not secured by the property, so the loan stays with you after the sale. Most have no prepayment penalty, but verify in the loan agreement before you sign.
Are contractor financing offers like “12 months same as cash” worth it?
Sometimes — but read the fine print. Many are deferred-interest plans: miss the promo deadline and interest is charged retroactively from day one, often at 20%+ APR. They work only if you are certain you can pay in time.
Educational content only — not financial advice. Loan terms, rates and approval depend on the lender and your profile. See our Financial Disclaimer.